Marcus-Dyer_Web

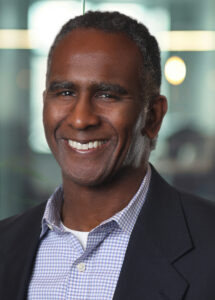
Marcus Dyer

JD, CPA Principal, Co-leader of Tax Controversy

Get to Know Me

Marcus is a principal with over 15 years of providing tax and business advisory services.

As one of the leaders of Withum’s Tax Controversy practice, he has extensive experience in resolving federal, state and local tax controversies including, but not limited to, matters involving Tax Examinations, Appeals, Collections, Innocent Spouse, Responsible Party, and Offer-in-Compromise.

In addition, he has experience in the field of law representing clients in commercial and tax disputes before state courts, Federal District Court and the United States Tax Court. Marcus also has extensive experience in alternative dispute resolution, which he frequently used to resolve disputes by means other than litigation.

As for business transactions, he has experience in drafting, reviewing and negotiating the language of a wide array of transactions documents including, but not limited to, buy/sell agreements, portfolio management agreements, swap agreements, limited liability company agreements and indentures.

He is admitted to practice law in Federal District Court as well as United States Tax Court.
Service Expertise

Learn More About My Story

Learn more about my professional experience and how I spend my time outside the firm.

Education:

  • Juris Doctor, University of Pennsylvania
  • MPA, Public Finance, University of Texas at Austin
  • Bachelor of Arts, Duke University


Professional Affiliations:

  • Member, American Association of Certified Public Accountants (AICPA)
  • Member, New Jersey Society of Certified Public Accountants (NJCPA)
  • Member, New Jersey State Bar Association


Authored Insights

Read more
hand holding a clock with money
Government’s Kwong Appeal Explains Its Position on Broad COVID-19 Refund Claims

On September 16, 2026, the federal government filed its appellate brief in the case of Kwong v. United States, a closely watched case that could determine whether taxpayers may rely on COVID-19 disaster relief to revive otherwise time-barred refund claims. In seeking reversal, the government argues that the Court of Federal Claims transformed temporary disaster…

Read more
us capitol with blue and purple lighting and a connected framework background.
Bowen v. Commissioner Narrows the Scope of Landmark COVID-Era Tax Relief

The Tax Court’s recent decision in Bowen v. Commissioner provides new guidance on the scope of potential Covid-era refund claims arising from Kwong v. United States. To understand the ramifications of Bowen for taxpayers who are potentially eligible for refunds under Kwong, it is helpful to begin with what the Kwong case established. What Kwong Established The…

Read more
us capitol with american flag in background
IRS Signals Preparations for Potential Kwong Refunds as July 10 Deadline Approaches

IRS Chief Tax Compliance Officer Jarod Koopman recently indicated that the IRS is considering creating a portal, in light of Kwong v. United States, 178 Fed. Cl. 295 (2025), to help taxpayers who may be entitled to refunds of COVID-era interest and penalties submit and track their refund claims. The announcement comes as the IRS…